“Someday financial markets will decline...rising stock/bond markets will no longer be government policy. QE will end and money won’t be free. Corporate failure will be permitted. The economy will turn. Someday, somewhere, somehow, investors will lose money and once again come to favor capital preservation over speculation. Someday, interest rates will be higher, bond prices lower, and the prospective return from owning fixed-income instruments will again be commensurate with risk.” Seth Klarman
Tuesday, March 22, 2016
Why wait until it's been 20-30 years and it collapses...worthless. Is it time for your life insurance audit? From a foundation of ignorance...there is a wave coming...is your life insurance even competent?
"Is there a life insurance bubble that is about to go bust?
Life insurance buyers have two main options: term insurance that only pays if you die, or an insurance policy that has a savings or investment feature. That is often called universal or whole life. It's those types of policies, universal and whole life that we are talking about.
Transamerca Corporation no longer has its headquarters in the iconic Transamerca pyramid in downtown San Francisco. The signature building is still a part of the companies logo along with the words, "Transform tomorrow."
Mary and Gordon Feller bought Transamerica policies back in the 1980s and say the company has indeed transformed their tomorrow.
"The projections we were given were based on eight percent interest rate and there was never a time where the policies earned eight percent," Mary Feller said. "Now, suddenly the cost of the insurance has skyrocketed. So when we put in $250 or $500 or $700, or whatever we put in on that quarterly basis, that money is eaten up."
"Well, here we are 25 years later. The baby boomer generation is ready to retire. Now the companies say, 'Whoa, we've got to make good on our promise? No, we're walking away,'" said the Feller's attorney Harvey Rosenfield...."
LINK
Monday, March 7, 2016
"Is This Entire Rally Just One Big TRAP?"
"Few analysts realize that the sharpest, most aggressive rallies occur during bear markets. The reason for this is that during bear markets, investors tend to go short (borrow shares to bet on a collapse).
So when the market rallies even a little bit, it often will go absolutely vertical as these individuals panic and cover their shorts (which increases the buying power of the move).
Consider the Tech Bubble. When it burst, we had THREE monster rallies of 17%, 33% and 16% in just SIX months time!
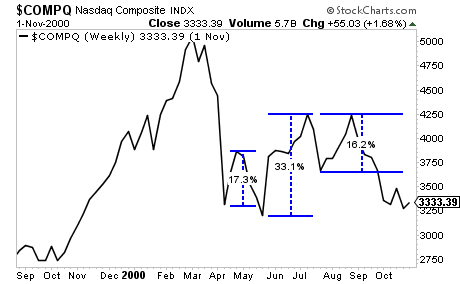
Anyone who bought into these moves for the long-term ended up get crushed as the market soon rolled over and worked its way down.
The below chart gives some perspective on just how much further stocks would fall relative to these bull traps!
Smart investors, however, used those rallies to prep for the next round of the drop. They didn’t get suckered into believing that it was the beginning of the next bull market...."
Graham Summers, Phoenix Capital Research
Tuesday, March 1, 2016
Friday, February 26, 2016
My Mutual Disability Insurance Policy vs. Your Medical Association Discount Policy: It Matters
(Photo credit: Werner Elmker, Fairfield, Iowa)
(This is the first article in a series on income protection / disability insurance. It is a somewhat condensed version of a series of articles to come.)
The number one thing to understand about insurance is that quality is not available without personal service. It’s simply too complex. Try to find quality on the internet. I have. Each person’s financial circumstance is unique. In my experience, the internet products are not only inadequate, they are not even comparable…but they are…beguiling.
First, let’s briefly ask the question: WHY do you want income protection?
Your ability to work is the most valuable asset you own.
Let’s prove it.
Earning 200k per year for the next 35 years is a $7M ASSET.
If you owned a $7M home, would you insure it?
Now, let’s compare two sample disability insurance policies. We’ll call them My Mutual and My Medical Association Discount policies. Let’s see how well they protect your $7M asset, in the most critical provision in your entire policy—partial or temporary disability coverage.
PARTIAL DISABILITY BENEFITS?
- My Mutual Disability Policy: Yes. The Gold Standard.
- Medical Association Discount: Yes. Kind of….
What do you think is more likely to happen during your working lifetime: 100% disability with an inability to do anything, permanently?
… OR …
Temporary (i.e. serious illness, then recovery) or partial disability?
Correct!
So where do you think you should have a STRONG contract in case you need it? This is THE MOST CRITICAL part of your disability insurance contract.
I cannot emphasize this enough!
The Medical Association Discount Policy will cover a loss in income if it exceeds 20% of your income. And ONLY IF you first receive benefits for TOTALdisability. (Read CAREFULLY.)
On the other hand, My Mutual DOES NOT REQUIRE TOTAL DISABILITY FIRST, for benefits. To qualify, they require 1 of 3 possibilities: loss of the ability to perform 1 main duty OR loss of 15% of your income OR the loss of 15% of your time.
On top of that, the MINIMUM they will pay you for the first 12 months is50% of your benefit or the actual loss, WHICHEVER IS GREATER.
After 12 months, benefits are proportionate to the loss of income. At any time,the full benefit will be paid if the loss is greater than 75%.
ANOTHER CRITICAL POINT for physicians. How will the insurance company determine how much my monthly benefit amount is?
Most disability insurers will only go back 12-24 months, maybe 3 years, often based on your tax return filings. Suppose the last couple of years were not so good, but prior to that your income was excellent.
You’ll like this.
My Mutual’s definition of pre-disability income is extraordinary: You have 3 choices:
- Average monthly income for the last 12 months; OR
- the last 24 months; OR
- ANY consecutive 24 months during the previous 60 months prior to disability
WHICHEVER IS HIGHEST!
What about inflation?
At 44 years old (if disabled at 35) with 3.1% inflation, you will need DOUBLEyour monthly income just to maintain your initial standard of living.
My Mutual’s policy will increase your pre-disability income (by which your benefit is calculated) DURING your disability, by a MINIMUM of 3% and aMAXIMUM of No Cap. Nobody competes with that - let alone an internet policy.
It’s the gold standard for a reason.
Remember, you will not realize this until it is too late.
It’s almost as if someone actually took the time to THINK, “Hmm…what is the most critical piece of a disability insurance policy? And how can we make it the STRONGEST part, the foundation of our coverage?”
Imagine that!
Thinking about benefiting policyholders as opposed to “How can we defend ourselves against claims and increase our (short-term) profits (to please Wall Street)?”
Who do you want standing behind you?
I know who I want.
Can anyone compete with My Mutual?
In the most critical areas?
I don’t know.
But I’ve yet to see it, and doubt it.
(I’ve got the spreadsheets.)
Talk to someone who seriously cares. Someone who ENJOYS discerning details. Details that matter TO YOU.
As a busy physician, I’d want the kind of person I’m confident is already turning over every rock so I don’t have to. That’s what you do for your patients. You expect the same.
… OR …
Learn a “new specialty” in your “spare” time (not!).
What is the take-away?
FUNDAMENTALLY, realize that all accurate actuarial calculations are the SAME. That is, THERE ARE NO REAL DISCOUNTS IN INSURANCE WITHOUT CUTTING BENEFITS! There is just sales and marketing…to beguile you.
Good pricing can only be accomplished by outstanding underwriting, comprehension, and control of one’s risk pool. As history shows, indiscriminate “marketing discounts” have put many a youthful insurer into rehabilitation… especially during an economic downturn.
If you want to insure the most critical asset you own, you don’t look casually.
If the price is too good, then get out your magnifying glass and waste a day (or more) on becoming a contracts lawyer. Even then, it’s still hard to catch all the fine points, because this is NOT your niche.
Better: Find a specialist. Your time is valuable. And time off matters to your performance in growing the most valuable asset you own - your ability to work.
If professional discernment matters, find someone who thinks like you do. Who turns over every rock and inventories the entomological fauna before advancing.
Make sure he won’t settle for anything less than an A++, in anything… because you won’t either. That’s why people entrust you…with their breath.
FOR FURTHER
INFORMATION OR QUESTIONS, PLEASE CONTACT:
Robert S. Park, M.D.
Life Insurance+
Seattle, Washington
(206) 395-9501
wealth | estate | business planning
“Twenty years
from now you will be more disappointed by the things you didn’t do than by the
ones you did.” Mark Twain
Preserving your Savings in Safety

Subscribe to:
Posts (Atom)


